- Home
- Industries
- Banking & Financial Institutions Technology Architecture | Routeget
Digital Transformation for Banks and Financial Institutions
Banks run on trust, control and uptime. Routeget helps institutions modernise architecture and data so channels, risk and finance share one reliable foundation.
30+
clients served
$15M+
Savings Delivered
15+ yrs
Serving the Sector
20+
Projects Delivered
Banking and Financial Institutions: where the market stands today
A fact base for planning. All figures below are third-party research estimates, not Routeget data, and they differ by how each firm defines the market.
Digital banking and modernisation
Customers expect digital-first service, while banks work to retire legacy platforms and manage risk.
About US$2.0 trillion in retail banking
Grand View Research sizes global retail banking at over US$2.03 trillion; McKinsey reports sector profits above US$1.3 trillion a year.
About 4.5% to 8.7% CAGR
Publishers project banking growth of 4.5% to 5.8%, with digital banking near 8.7%.
Architecture, data and straight-through processing
Modern architecture and clean data shorten product launches and cut manual work.
Sources: Grand View Research; McKinsey; Market Research Future; Databridge Market Research. Figures vary by publisher and definition; verify before external citation. Estimates retrieved October 2026 and subject to each publisher’s definitions; verify against the publisher before citing externally.
End-to-end digital transformation
Strategy, platform selection, integration and data work delivered as one programme.
Regulated finance data models
Accounts, positions, policies and ledgers structured for reconciliation and audit.
Risk and compliance visibility
Controls, approvals and evidence captured as part of the workflow.
Secure integration
Connections between core, channel, reporting and finance systems with strict access control.
Four pressures that shape banking & financial institutions operations
These are the recurring problems we see when core, channels, risk, finance and operations technology run on disconnected systems.
Risk and compliance data
Risk numbers come from separate extracts that are hard to reconcile.
Channel consistency
Branch, mobile and web channels show different information.
Capabilities built for core, channels, risk, finance and operations technology
Pick the area closest to your priority. Each can be delivered on its own or as part of a wider programme.
Hold one trusted record for banking services.
- Customer, account and relationship data in one model
- Onboarding and verification workflows
- Consent and data-protection records
- Service requests and case history
Keep every transaction reconciled.
- Ledger, sub-ledger and reconciliation controls
- Payments, settlements and exception handling
- Period close and consolidation
- Audit trails for every posting
Make controls visible and evidence ready.
- Policy, limit and approval workflows
- Regulatory reporting data preparation
- Monitoring and alert investigation
- Evidence capture for audits
Serve customers and see performance.
- Digital and branch channel integration
- Product and portfolio performance reporting
- Customer profitability analysis
- Forecasting and scenario views
Two scenarios where connected data changes the day-to-day
These are illustrative scenarios that describe the business objective. They are not customer case studies.
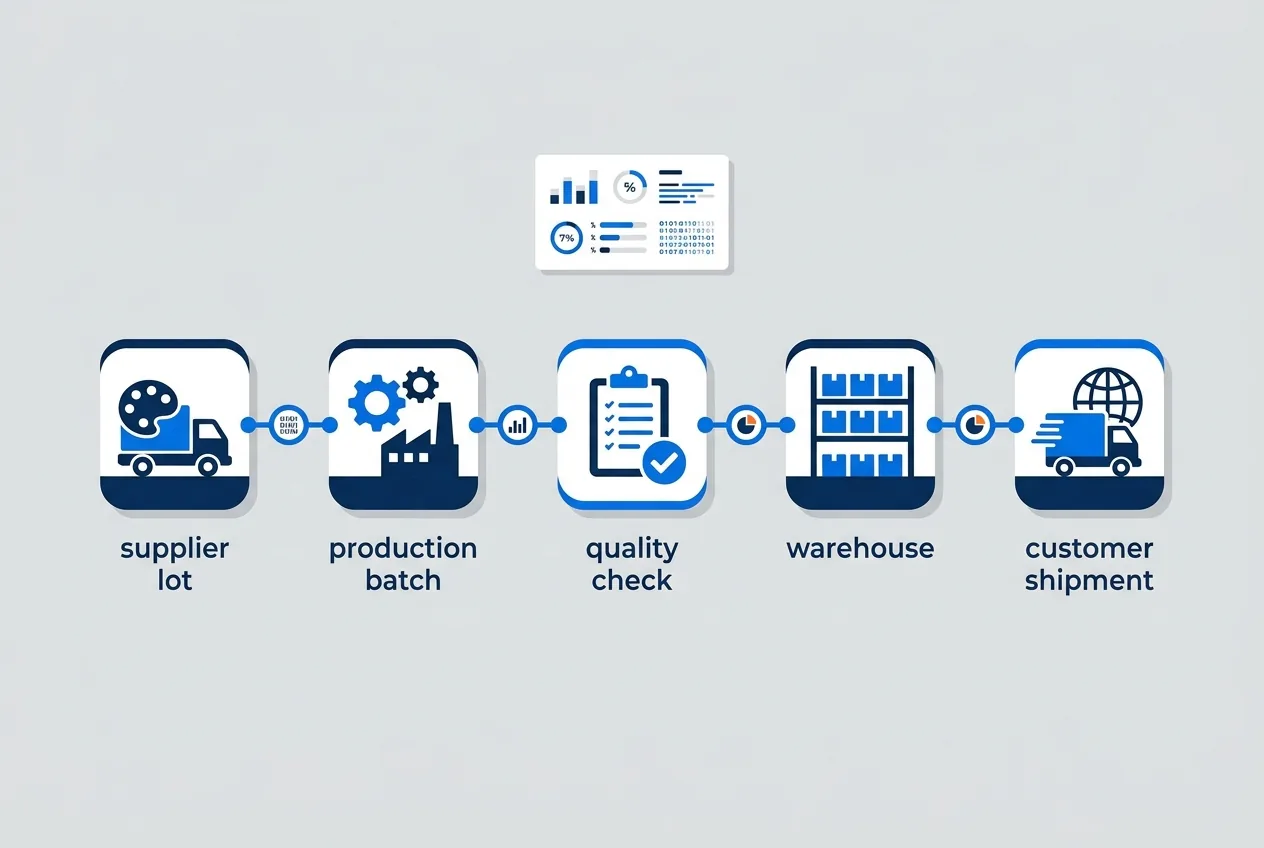
Modernising in safe steps
A phased plan moves capabilities off the legacy core while it keeps running.
Business objective: reduce risk and show value early.
Reconciling risk and finance data
Common data definitions give risk and finance consistent numbers.
Business objective: cut manual reconciliation.
How we approach delivery and evidence outcomes
We do not publish unverified customer figures on industry pages. This is how we make outcomes measurable in an engagement.
Baseline first
We agree the starting measures with you before design, such as time to launch a product, straight-through processing and cost-to-income ratio.
Delivery in stages
Releases are phased by site and process, so each stage is tested against real operations before the next.
Measured against your targets
Dashboards report the baseline measures from go-live, so benefit is judged on your data.
Examples of Routeget engagements can be discussed in a discovery call, subject to client approval for each reference.
Why Routeget for banking & financial institutions
We bring a delivery approach built around the realities of legacy cores, heavy regulation and rising customer expectations.
Architecture and data depth
We map systems, interfaces and data lineage so modernisation proceeds in safe steps.
Integrated, not stitched together
Core, channels, risk, reporting and finance share one data model, so operational and financial records reconcile.
Phased, low-disruption rollout
We plan releases around regulatory deadlines, product launches and platform renewals to protect service levels.
Data you can act on
Analytics are designed with your operations team, so measures reflect how your plants actually run.
Related reading from the Routeget team
Perspectives on the supply chain, data and integration topics behind this industry.
Why Automating our Supply Chain is Crucial to your Business Success
Why supply chain automation matters for service levels, cost and resilience.
The Evolving Landscape of Data Modernization Engineering
Trends in data modernization engineering and how they affect enterprise platforms.
AI attracts a new generation while assisting Argentine small producers and winemakers in competing
How AI is helping small producers compete in demanding markets.
Explore adjacent industry practices
Plan your banking & financial institutions digital foundation with Routeget
Book a 30-minute discovery to walk through your core platforms, channels, risk systems and data stores and your priorities with a Routeget industry specialist.
Your details are used only to respond to this enquiry. See our Privacy Policy.
Banking & Financial Institutions: questions buyers ask us
How do you engage with a banking & financial institutions business?
We usually start with a short discovery and a process review of one journey such as account opening. From there we propose a phased scope, which can be fixed-scope for defined releases or a time-and-materials team for ongoing improvement.
Do you replace the core banking system?
We advise on architecture and phasing and implement according to your chosen platform strategy.
How do you manage regulatory risk?
Changes are planned with control, testing and audit evidence at each step.
Who owns the data and the configuration?
You do. The solution runs in your own environment, and configuration, data models and reports are documented and handed over so your team can maintain them.
How do you approach pricing and timelines?
Pricing and timing follow scope, including the number of products, channels and legacy platforms. We share an estimate after discovery, with assumptions and exclusions stated, and we confirm timelines only after reviewing your landscape.